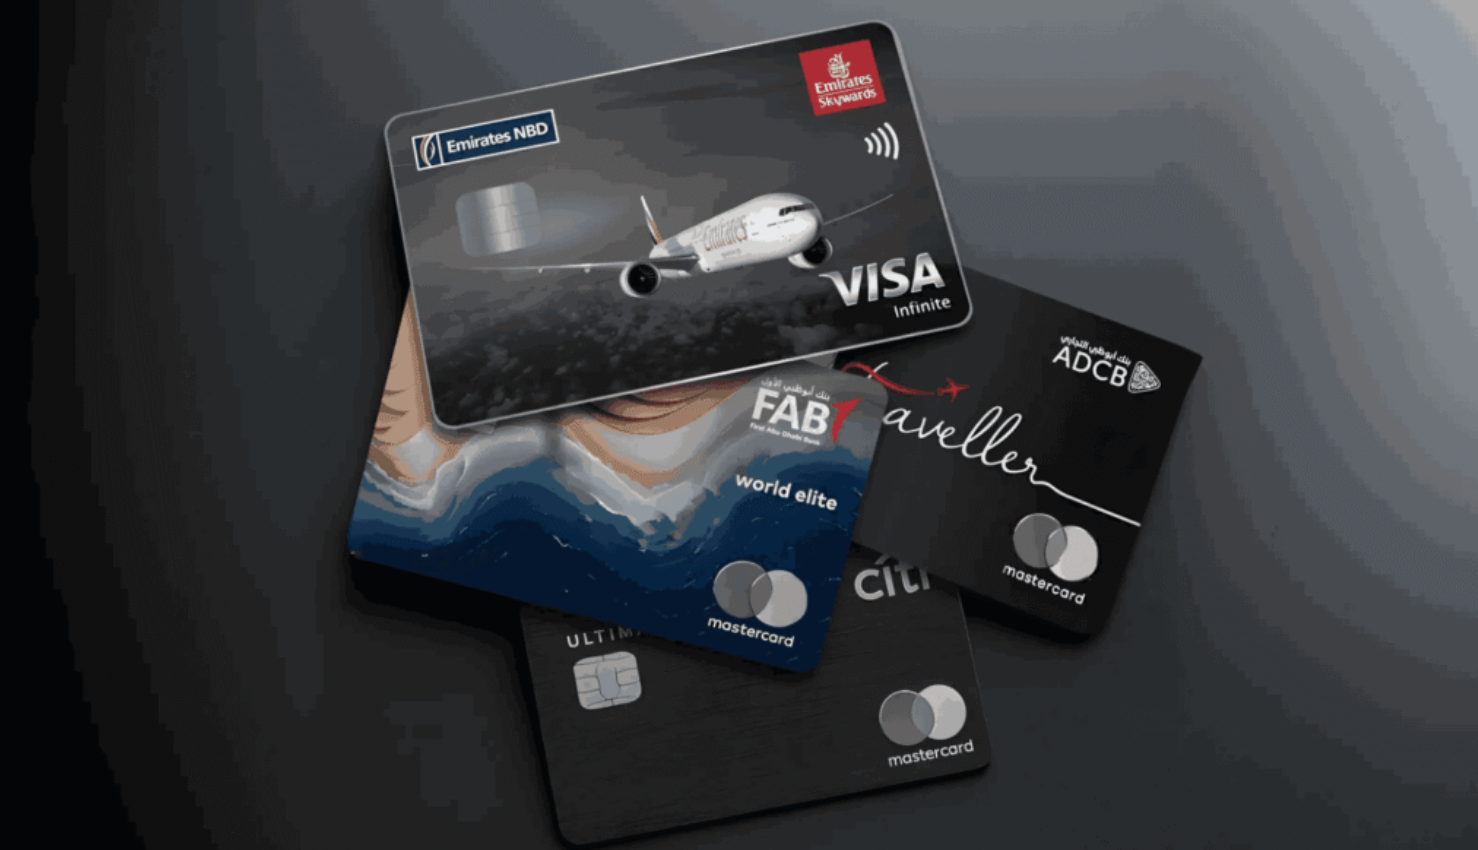
A couple planning their first international trip in years opened three different credit card applications in a single weekend after a friend mentioned earning enough points to fly business class nearly free. Two months later, one card sat unused because its points required a transfer partner they never researched, while the other became their default for every purchase because its earning categories matched their actual spending.
The gap between those two outcomes usually comes down to matching a card’s structure to real habits rather than chasing the most talked-about welcome bonus.
Earning Rates Across Spending Categories
Travel cards differentiate themselves largely through bonus categories, where certain purchases earn a higher multiplier than the standard rate. The Chase Sapphire Preferred earns a strong multiplier on travel and dining, categories that suit people who eat out often and book trips directly rather than through third parties. The American Express Gold Card leans heavily into dining and grocery spending, a combination that benefits people who cook at home frequently but still eat out regularly.
- Flat-rate cards: earn the same multiplier on every purchase, simplifying tracking at the cost of maximizing bonus categories.
- Rotating category cards: offer higher rates on categories that change quarterly, requiring more active management.
- Fixed bonus category cards: consistently reward specific spending areas like travel, dining, or groceries.
- Portal-boosted rates: some cards offer their highest multiplier only when booking through the issuer’s own travel portal.
Matching a card’s bonus categories to actual monthly spending, rather than to an idealized budget, tends to produce far more value than chasing whichever card has the highest advertised earning rate.
Pulling several months of past statements and sorting spending by category is a practical exercise that reveals far more than guessing at habits from memory. Many cardholders assume dining or travel dominates their budget, only to find that groceries, streaming subscriptions, or general online shopping make up the larger share of monthly spend. A card chosen based on this kind of honest review tends to earn more points over a year than one chosen because it sounded appealing during a flashy marketing campaign.
Transfer Partners and Point Valuations
The real value of a rewards program often depends on its airline and hotel transfer partners rather than the raw number of points earned. Chase Ultimate Rewards points transfer to partners including United, Southwest, and Hyatt, giving cardholders flexibility to find strong redemption value depending on where they want to travel. American Express Membership Rewards points offer an even broader partner network, including several international carriers that can unlock outsized value for premium cabin redemptions on long-haul flights.
Point valuations swing dramatically depending on how they are redeemed. Transferring points to an airline partner for a premium cabin seat on a long international flight often yields far more value per point than redeeming the same points for a statement credit or a domestic economy ticket, which is why frequent international travelers tend to favor transferable point currencies over cash-back-style travel cards.
Sweet spots, specific redemptions where a transfer partner’s award chart delivers outsized value relative to the points required, are a well-known concept among frequent point users and can change over time as airlines adjust their own charts. Following dedicated points and miles communities or newsletters helps cardholders stay current on these opportunities, since a sweet spot that existed a year ago may have been quietly adjusted away, and chasing outdated advice can lead to disappointment when a previously generous redemption no longer exists on a current award chart.
- Chase Ultimate Rewards: transfers to partners including United, Southwest, and Hyatt among others.
- Amex Membership Rewards: a broad partner network including several international carriers for premium cabins.
- Award chart research: check current transfer ratios and partner charts before assuming an old redemption still holds.
- Timing transfers: move points to a partner only when ready to book, since transfers are typically irreversible.
Lounge Access and Airport Perks
Airport lounge access has become one of the most visible perks separating premium travel cards from mid-tier options. The American Express Platinum Card offers access to Centurion Lounges along with a broad network of Priority Pass lounges, a benefit frequent travelers often cite as worth a sizable share of the card’s annual fee on its own. The Chase Sapphire Reserve provides Priority Pass access as well, though without the same tier of dedicated Centurion Lounges that Amex Platinum cardholders can use.
- Priority Pass membership: grants access to a broad network of lounges across many airports worldwide.
- Airline-specific lounges: some premium cards include access tied to a specific partner airline rather than a general network.
- Airport fee credits: annual statement credits for programs like TSA PreCheck or Global Entry reduce security wait times.
- Companion passes and guest access: some lounge memberships allow a limited number of guests to enter alongside the cardholder.
Lounge access delivers the most value for travelers who fly frequently enough to use it regularly, while occasional travelers may find the annual fee difficult to justify against a benefit they rarely access.
Lounge crowding has become a growing concern at major hub airports as more premium cards grant access to a widening pool of travelers, occasionally leading to long waits or overcrowded lounges during peak travel periods. Some issuers have responded by introducing per-visit fees or guest limits for cardholders who bring companions frequently, and a few premium cards have begun restricting access at their most popular locations to preserve the experience for members carrying the top tier of the card.
Annual Fees Versus Redemption Value
Premium travel cards carry annual fees that can run into the hundreds of dollars, and evaluating whether a card is worth that cost requires an honest look at how many of its included perks really get used. A card bundling airport lounge access, an annual travel credit, and hotel status can offset its fee entirely for someone who travels several times a year, while the same card offers far less value to someone who travels once annually and skips most of the included benefits.
Mid-tier cards with lower or no annual fees often make more financial sense for occasional travelers, since the bonus categories and modest sign-up bonus can still deliver solid value without the pressure to use premium perks that would otherwise go to waste. Running the math on included credits against the annual fee, rather than assuming a premium card is automatically worth it, avoids paying for benefits that go unused.
Many premium cards bundle credits toward specific categories, like a dining credit or a rideshare credit, that only count toward the fee’s value if the cardholder spends in those exact categories within the required timeframe. A credit that expires unused, because it requires booking through a specific portal or reaching a spending threshold most people never hit naturally, should not be counted the same way as cash-equivalent value when weighing a card’s true cost against its benefits.
Sign-Up Bonuses and Spending Thresholds
Welcome bonuses remain one of the fastest ways to accumulate a large point balance, often worth more than a full year of regular spending on the card. These bonuses typically require hitting a spending threshold within the first three months of account opening, and cardholders should confirm that threshold fits naturally within planned spending rather than resorting to unnecessary purchases just to qualify.
Card issuers also enforce rules limiting how often someone can earn a bonus on the same card, commonly known informally as the “5/24 rule” at Chase, which restricts approval for applicants who have opened five or more new cards across any issuer within the past twenty-four months. Knowing these eligibility rules before applying prevents a wasted credit inquiry on a card that will get denied anyway.
Timing applications around a known large expense, like a planned home renovation or an annual tax payment, can make hitting a spending threshold easier without artificially inflating spending just to chase a bonus. Applicants juggling multiple card applications should also space them out by at least a few months where possible, since a cluster of recent applications can lower approval odds even for someone with a strong credit history and a track record of responsible card use.
Foreign Transaction Fees and International Use
Foreign transaction fees, typically around three percent of each purchase, can quietly erode the value of using a card abroad if the card was not designed for international travel. Most dedicated travel cards waive this fee entirely, while general-purpose cash-back or store cards frequently still charge it, making them a poor choice for use during international trips even if they offer solid domestic rewards.
Chip-and-PIN functionality and wide acceptance also matter for international use, since some merchants and transit systems outside the United States still favor chip-and-PIN over the chip-and-signature system more common domestically. Confirming a card’s international acceptance and fee structure before departure avoids unpleasant surprises on a first statement after returning home.
Dynamic currency conversion, a practice where a foreign merchant offers to charge a purchase in the cardholder’s home currency instead of the local one, typically carries a worse exchange rate than letting the card network handle the conversion directly. Declining this option at checkout, even when a cashier or terminal presents it as a convenience, almost always saves money compared with accepting the merchant’s own conversion rate, a small habit that adds up over the course of a longer international trip.
Comparing Chase, Amex, and Capital One
Chase’s Sapphire lineup remains a strong entry point for travelers new to points strategy, offering solid transfer partners and straightforward bonus categories without requiring deep program knowledge to extract good value. American Express leans into premium perks and a broader luxury travel partner network, appealing more to travelers who fly premium cabins or stay at high-end hotel chains regularly. Capital One’s Venture line offers a simpler flat-rate earning structure alongside a growing set of transfer partners, appealing to people who want strong rewards without managing multiple bonus categories.
- Chase Sapphire cards: strong for travel and dining categories with a well-regarded transfer partner network.
- American Express cards: strongest for premium lounge access and luxury hotel and airline partnerships.
- Capital One Venture cards: simpler flat-rate earning with growing transfer partner options and lower complexity.
- Co-branded airline and hotel cards: best for loyal customers of a specific airline or hotel chain seeking elite status perks.
None of these issuers is a universal best choice, and the right pick depends heavily on which airlines and hotel chains a traveler already favors.
Smaller issuers and credit unions have also entered the travel rewards space with competitive offerings, sometimes undercutting the larger banks on annual fees while still providing solid earning rates and reasonable transfer options. These smaller programs rarely match the scale of Chase, Amex, or Capital One in terms of partner networks, but they can suit a traveler whose needs are simpler and who values a lower fee over an expansive list of transfer options they may never fully use.
Choosing a Card for Travel Habits
The most effective approach starts with an honest review of recent spending and travel patterns rather than choosing based on which card a friend recommends. Frequent international travelers benefit most from transferable points, lounge access, and no foreign transaction fees, even at the cost of a higher annual fee. Occasional domestic travelers often get better value from a lower-fee card with strong everyday bonus categories and a straightforward cash-back-style redemption option.
Cardholders willing to manage multiple cards can build a small portfolio pairing a premium travel card for lounge access and transfer flexibility with a no-fee cash-back card for categories the travel card does not reward well, extracting more overall value than relying on a single card for every purchase.
A useful habit for any cardholder, regardless of how many cards they carry, is revisiting the entire card lineup once a year around the time an annual fee posts. Spending patterns shift, issuers adjust benefits, and a card that made sense two years ago may no longer fit current habits, making this annual check-in a simple way to catch a card that has quietly stopped earning its keep.
Downgrading to a no-fee version of the same card, when an issuer offers one, is often a better option than closing an old account outright, since account age contributes to overall credit history and closing a long-held card can shorten that history unnecessarily. A brief call to the issuer’s retention line before deciding to cancel can also surface a retention offer, such as a statement credit or a reduced fee, that makes keeping the card worthwhile for another year.
Final Thoughts
Travel credit cards reward people who match a card’s structure to their actual spending and travel patterns rather than chasing whichever offer looks most impressive at first glance. Earning categories, transfer partners, and included perks like lounge access all matter differently depending on how often someone flies and where they tend to go. A premium card with a high annual fee can deliver strong value for a frequent traveler while sitting mostly unused in a drawer for someone who travels once a year.
Reviewing spending habits honestly before applying, and revisiting that fit periodically as travel patterns change, keeps a card working as an asset rather than a forgotten fee on an annual statement.
Frequently Asked Questions
Do travel credit card points expire?
Policies vary by issuer, but many major transferable point programs like Chase Ultimate Rewards and Amex Membership Rewards do not expire as long as the account remains open and in good standing. Airline and hotel loyalty points transferred out of these programs may carry their own separate expiration rules once transferred.
Is it worth paying an annual fee for a travel card?
It depends on whether the included perks, such as lounge access, travel credits, or bonus categories, add up to more value than the fee itself based on actual travel habits. Frequent travelers often recoup the fee easily, while occasional travelers may find a no-fee card delivers better net value.
Can points be transferred between different reward programs?
Points generally transfer from a bank’s rewards program, like Chase Ultimate Rewards, to specific airline and hotel partners rather than between unrelated bank programs. Transfer ratios and available partners vary by issuer and can change over time, so checking current partner lists before applying is worthwhile.
How many travel credit cards should someone realistically carry?
There is no fixed right answer, though many points strategists suggest one premium travel card for perks alongside one or two cards covering everyday bonus categories the premium card does not reward well. Managing too many cards can lead to missed annual fees or underused benefits that outweigh the rewards earned.
Do travel cards help build credit history?
Responsible use of any credit card, travel-focused or otherwise, can help build credit history through on-time payments and manageable utilization. Opening several cards in a short period to chase sign-up bonuses can temporarily lower a credit score, so pacing applications matters for anyone also focused on credit building.
What happens to travel card perks if the annual fee changes?
Issuers occasionally adjust the fee and benefits attached to a card, and existing cardholders are typically notified in advance of such changes with the option to downgrade to a no-fee card if the new terms no longer make sense. Reviewing a card’s value annually, rather than assuming the original terms remain unchanged indefinitely, is a good habit for any long-term cardholder.