A profitable business closes its doors. Not because the product failed, not because customers stopped buying, but because the money simply wasn’t there when the bills came due. This scenario plays out more often than most people realize, and cash flow problems sit right at the center of it.
Knowing what cash flow management actually involves, and why even profitable businesses can run into serious trouble without paying proper attention to it is essential knowledge for anyone running, or planning to start, a business.
What Cash Flow Management Actually Means
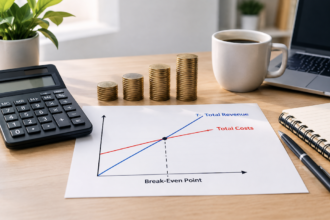
Cash flow management is the ongoing process of monitoring, analyzing, and optimizing the actual movement of money into and out of a business, making sure enough cash is available to meet obligations as they come due. This is meaningfully different from simply tracking profitability. A business can show strong profit on paper while still facing serious, immediate cash shortages that threaten day-to-day operations.
Profit measures revenue minus expenses over a period. Cash flow tracks the actual timing of money moving in and out. That timing gap, not the underlying numbers themselves, is what creates operational crises even within businesses that are, on paper, entirely healthy.
How a Profitable Business Runs Out of Cash
Customers often take considerable time to actually pay invoices, even for work that’s already been completed and delivered. Businesses frequently need to pay suppliers and expenses before they’ve received payment from their own customers. Rapid growth can strain cash flow badly, since growth almost always requires upfront investment before the returns show up. Seasonal businesses can face cash flow challenges during slow periods despite strong overall annual profitability.
That payment timing gap is probably the single most common source of trouble for otherwise healthy businesses. A business completes profitable work, immediately incurs the associated costs, materials, labor, and then waits thirty, sixty, sometimes ninety days for the customer to actually pay. During that gap, the business still has to cover its own ongoing expenses, despite having technically already earned, but not yet collected, the money.
The Three Components of Business Cash Flow
Operating cash flow reflects money generated or used through everyday business operations. Investing cash flow reflects money spent on or generated from longer-term investments like equipment or property. Financing cash flow reflects money from loans, investor funding, or debt repayment. Breaking things down this way helps pinpoint exactly where a specific cash flow problem is actually originating.
Why Forecasting Actually Matters
Forecasting helps identify potential future cash shortages before they turn into a crisis. That advance warning lets a business arrange financing or adjust spending proactively, before the problem fully materializes. Regular forecasting also builds an of typical cash flow patterns and seasonal swings over time.
Businesses that only discover cash flow problems after they’ve already happened face considerably more limited, and usually more expensive, options for fixing them. A business that forecasts and spots a shortfall weeks or months in advance can explore more favorable financing, adjust spending proactively, or take other strategic action before things become an actual emergency rather than reacting under pressure at the worst possible moment.
Common Mistakes That Show Up Again and Again
Focusing exclusively on profitability while neglecting to actually monitor cash position. Extending generous payment terms to customers without considering the resulting cash flow impact. Never building any cash reserve for unexpected expenses or temporary shortfalls. Underestimating how quickly rapid growth can strain available cash. Failing to follow up promptly on overdue payments.
That customer payment terms issue deserves special mention. Businesses eager to win customers sometimes offer increasingly generous terms without fully considering the cumulative impact, landing a lot of sales while simultaneously creating a significant, ongoing cash gap between when costs get incurred to fulfill those sales and when payment actually arrives.
Practical Ways to Improve Cash Flow
- Invoice promptly and follow up consistently on anything overdue
- Consider small incentives for customers who pay early
- Negotiate more favorable payment terms with your own suppliers when possible
- Build a cash reserve specifically as a buffer against shortfalls
- Review pricing regularly to make sure it actually reflects your true costs
Why a Cash Reserve Matters More Than People Think
A cash reserve provides a buffer against unexpected expenses or temporary revenue disruptions. It helps a business avoid unfavorable, expensive emergency financing during a rough patch, and it provides flexibility to actually pursue unexpected opportunities that need some upfront investment. Building that reserve takes real discipline, especially during periods when cash feels comfortably plentiful and setting some aside feels unnecessary.
Businesses without adequate reserves facing a sudden shortfall often end up accepting unfavorable financing terms, high-interest short-term loans, for instance, simply because they lack the cushion that would have let them weather the difficulty without resorting to something that expensive.
How Technology Makes This Easier
Accounting software automates invoicing and gives real-time visibility into cash position. Forecasting tools help project future cash needs more accurately. Automated payment reminders improve the consistency of following up on overdue invoices, cutting down considerably on the manual effort ongoing cash flow monitoring would otherwise require.
The Warning Signs Most Owners Miss Until Too Late
Certain patterns tend to precede a cash flow crisis, and recognizing them early gives a business real room to act before things get desperate. Consistently dipping into a line of credit just to make payroll is one. Increasingly delayed payments to your own suppliers is another, often the first visible sign that a business is quietly running on borrowed time. A growing gap between reported profit and actual bank balance is a third, and it’s exactly the kind of thing a business owner focused purely on the profit and loss statement can miss for months.
None of these signs are catastrophic on their own. The danger is in treating each one as an isolated, temporary blip rather than recognizing the pattern they form together.
Cash Flow Statements Versus the Rest of Your Financials
Many small business owners never learn to read a cash flow statement properly, leaning instead on the profit and loss statement or their bank balance as rough proxies. Those substitutes miss something important: a cash flow statement specifically separates operating, investing, and financing activity, making it possible to see whether a cash shortfall is coming from the core business struggling, or simply from a large one-time investment or debt repayment distorting the picture temporarily.
Learning to read this specific document, even at a basic level, tends to reveal problems, and opportunities, that the other financial statements simply don’t surface clearly on their own.
Seasonal Businesses Face a Different Version of This Problem
A retail shop that does most of its business in November and December, or a landscaping company earning almost nothing over winter, faces cash flow challenges that look nothing like the “customer paid late” scenario most cash flow advice assumes. These businesses need to plan their entire annual cash strategy around covering many consecutive months of low or negative cash flow using the surplus built during their peak season.
The mistake seasonal business owners most commonly make is treating a strong peak season as spendable profit rather than the buffer it actually needs to become. A disciplined seasonal business sets aside a specific, calculated portion of peak earnings specifically earmarked to cover the lean months, essentially treating their own future cash flow gap the same way they’d treat a loan they need to plan around repaying.
Final Thoughts
Cash flow management is a distinct discipline from simply tracking profitability, requiring careful attention to the actual timing of money moving through a business to avoid the surprisingly common scenario where profitable businesses hit real trouble anyway. why this happens, and putting practical strategies in place, forecasting, reserve building, better collection habits, provides real protection for building a more resilient business.
Frequently Asked Questions
1. What’s the actual difference between cash flow and profit?
Profit is revenue minus expenses over a period. Cash flow tracks the actual timing of money moving in and out. A business can show strong profit while facing cash shortages, simply because of timing gaps between earning revenue and actually collecting it.
2. How large a cash reserve should a healthy business keep?
It varies by industry and circumstances, though many financial advisors suggest covering at least several months of typical operating expenses, a buffer against disruptions or temporary shortfalls.
3. Can cash flow problems be fixed without taking on debt?
Often, yes, better collection practices, improved supplier terms, and more accurate forecasting can go a long way. Some situations need additional financing, but it’s worth exploring the cheaper, non-debt options first.
4. Why do rapidly growing businesses face particular cash flow trouble?
Growth often requires upfront investment in inventory, staffing, or equipment before the resulting revenue shows up, a timing gap where cash outflows precede the inflows growth is ultimately supposed to generate.
5. How often should a business actually review its cash flow?
Many financial experts suggest at least monthly, though businesses with tight margins or volatility may benefit from weekly monitoring to catch problems before they grow.
6. Is cash flow management more important for small businesses than large ones?
Arguably, yes, smaller companies typically have far less financial cushion to absorb disruptions compared to larger organizations, making proactive cash flow management particularly critical for small business survival.